 Usdfi
Usdfi: when to lend, add liquidity or lock tokens
USDFI is a DeFi protocol whose money markets, liquidity pools and token locks serve different purposes. Consider lending for variable interest on a supported asset, liquidity provision when exposure to both pool tokens is acceptable, or a STABLE or USDFI lock when gauge voting fits the intended holding period.
- Network context
- The main app identifies BNB Smart Chain. Access to a cross-chain swap or bridge does not establish that a lending market, pool or token lock is available on the destination network.
Lend for interest on a supported asset
Lending fits a position intended to earn interest in one supported asset without adding exposure to a second pool token. Borrowers fund the interest in USDFI Money Markets. Supplied assets generate receipt tokens called oTokens, whose conversion rate into the supplied asset accounts for accrued interest. An unchanged oToken count therefore does not, by itself, mean no interest has accrued.
Supply APYs can change at block level. The Lending guide describes no time-based lock, but withdrawal depends on the supplied tokens not being used as collateral and sufficient liquidity remaining unborrowed. This makes lending more flexible than a vote-escrow commitment, while leaving both the eventual return and immediate access dependent on market conditions.
Borrow against collateral for access to another token
Borrowing serves the separate job of accessing an available token without selling the supplied collateral. Assets must first be supplied and designated as collateral. Borrowing then creates a debt balance with variable interest. Asset-specific Collateral Factors constrain borrowing limits, while changes in collateral or borrowed-token prices can make a loan eligible for liquidation. Supplying without borrowing is the closer fit when earning interest is the only intended use.
Add liquidity when both pool assets fit
Providing liquidity supports token swaps while exposing the position to both assets in the trading pair. Entering with a single token does not preserve exposure to that token alone. Relative price movements can produce impermanent loss compared with holding the assets outside the pool.
The liquidity guide describes both one-click provision and manual LP-token creation. Each route requires the liquidity-provider token matching the pair and pool type. The position to check is the matching LP balance or its recorded stake. STABLE incentives for liquidity providers require an LP-token stake in the matching gauge and depend on its allocation, so having an LP position and receiving emissions are separate matters.
A swap is the appropriate function when the job is simply exchanging one token for another. Completing a swap changes the tokens held; it does not establish an ongoing liquidity-provider position.
Lock tokens for influence over pool incentives
Locking fits participation in gauge voting. STABLE is the governance token, and locking it creates veSTABLE. Locking the native soft-pegged stablecoin USDFI creates veUSDFI. Both vote-escrow forms provide gauge voting rights, with terms up to four years. Their token overviews describe a four-year lock as providing the maximum voting and reward boost.
Gauge votes influence the allocation of STABLE emissions during weekly epochs. Votes may also earn pool-specific incentives called bribes. A recorded lock and its voting power establish the governance position; they do not fix future fee income or voting incentives.
These locks are a weak fit for funds needed before the chosen term ends. Locking USDFI also retains its depeg risk: the token’s soft $1 target does not guarantee the market value of the locked balance or rewards.
Use Money Legos for an additional yield strategy
Money Legos fit the additional job of allocating eligible LP tokens to a yield strategy. The strategy stake is distinct from the underlying pool position. It adds exposure to the protocols the strategy uses, including their contract and liquidity risks. Applicable performance fees, underlying-protocol charges and blockchain transaction costs belong in the assessment of its proceeds.
Migration is a prerequisite for legacy Money Legos positions. USDFI’s migration notice says the old versions are no longer supported in their previous form and LP tokens need to move to the replacement system. Old strategy instructions should therefore not be treated as instructions for an unchanged active position.
When USDFI trades below its $1 target, the Boosted USDFI APR described in the Money Legos introduction includes potential upside from a return to the peg. That part of the displayed rate depends on recovery in the reward token’s price.
Decision checklist
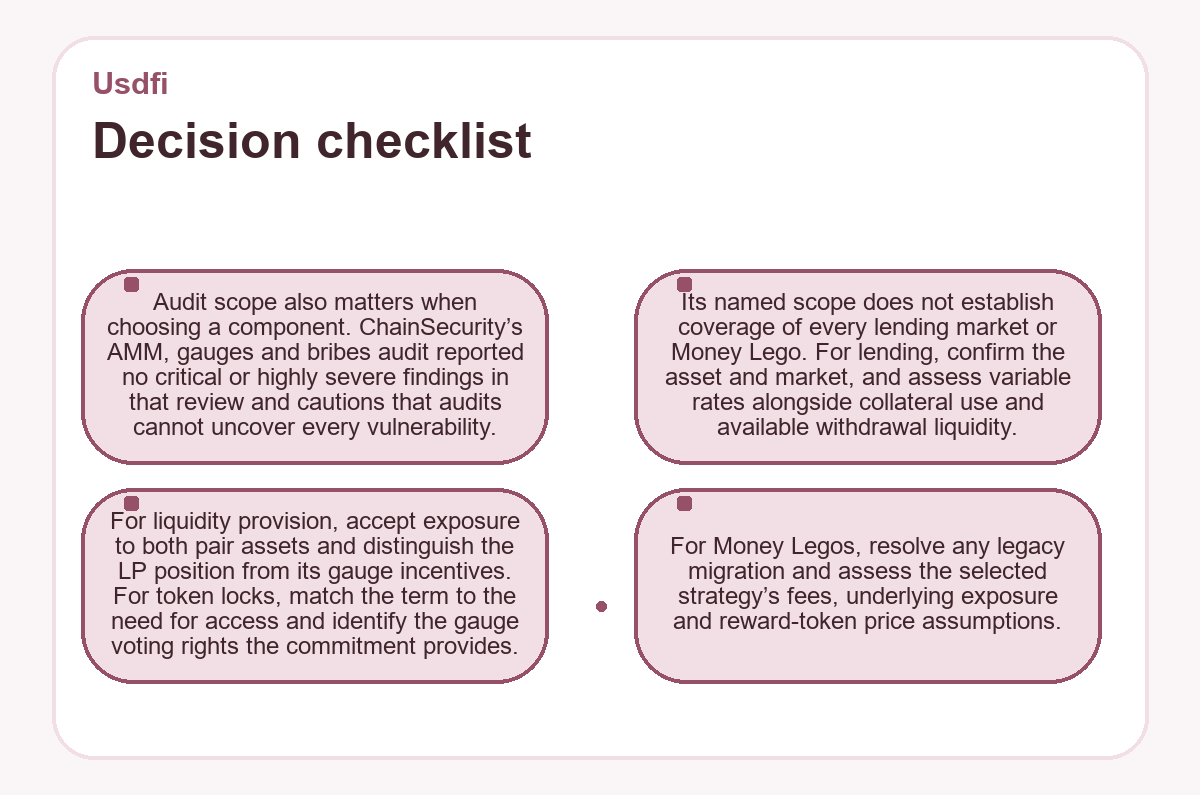
Audit scope also matters when choosing a component. ChainSecurity’s AMM, gauges and bribes audit reported no critical or highly severe findings in that review and cautions that audits cannot uncover every vulnerability. Its named scope does not establish coverage of every lending market or Money Lego.
- For lending, confirm the asset and market, and assess variable rates alongside collateral use and available withdrawal liquidity.
- For liquidity provision, accept exposure to both pair assets and distinguish the LP position from its gauge incentives.
- For token locks, match the term to the need for access and identify the gauge voting rights the commitment provides.
- For Money Legos, resolve any legacy migration and assess the selected strategy’s fees, underlying exposure and reward-token price assumptions.